Multifamily real estate has long been one of the most reliable ways to build wealth in the US. People always need a place to live, and apartment buildings generate steady rental income whether the stock market is up or down. But learning how to invest in multi family properties is not as simple as buying a house and renting it out. The numbers are bigger, the financing is different, and the risks are spread across dozens or hundreds of tenants rather than one.
This guide covers what you need to know to make your first multifamily investment or scale up your existing portfolio. We will go through why multifamily works, how to evaluate a deal, the financing options available today, the difference between syndication and direct ownership, and how to pick the right market. By the end, you should have a clear picture of whether multifamily investing fits your goals and how to get started.
The short version: multifamily rewards investors who treat it like a business. The numbers are driven by net operating income and cash-on-cash return, the loans are commercial above four units, and the market you pick matters as much as the property.
Why Multifamily?
Multifamily investing means owning apartment buildings with five or more units, though many investors start with smaller properties in the two to four unit range. The appeal is simple: more units mean more income streams, and if one tenant moves out, you still have rent coming in from the others. That diversification reduces the risk that a single vacancy will wipe out your cash flow.
The numbers show why investors like this sector. Small multifamily originations reached an annualized pace of $71.6 billion through the first half of the year, exceeding the prior full-year total of $69.6 billion by 2.8%. Fannie Mae and Freddie Mac have combined loan purchase caps of $176 billion for the current year, up more than 20% from the prior year, which means there is plenty of capital available for well-run properties. That liquidity keeps the market functioning even when interest rates are higher than they were a few years ago.
Multifamily also offers tax advantages that single-family rentals do not. You can depreciate the building over 27.5 years, deduct mortgage interest, and use cost segregation studies to accelerate depreciation in the early years. Those paper losses can offset rental income and reduce your tax bill. When you sell, you can roll gains into another property through a 1031 exchange and defer the taxes again.
The downsides are real. Multifamily is management-intensive. You need systems for finding tenants, handling repairs, and collecting rent. Or you need to hire a property manager, which takes 8% to 10% of gross rents. Financing is also harder than buying a single-family home. Commercial loans require larger down payments, usually 20% to 30%, and lenders look closely at the property income, not just your personal credit. If you are comparing this to owning a single house, our breakdown of rental property ROI covers the numbers on the smaller end.
Multifamily is a business, not a side hustle. The investors who do well treat it like a business from day one.
How to Evaluate a Multifamily Deal
Evaluating a multifamily property comes down to the numbers. You need to know what the property earns, what it costs to run, and what you are paying for it. The two most important metrics are cap rate and cash-on-cash return.
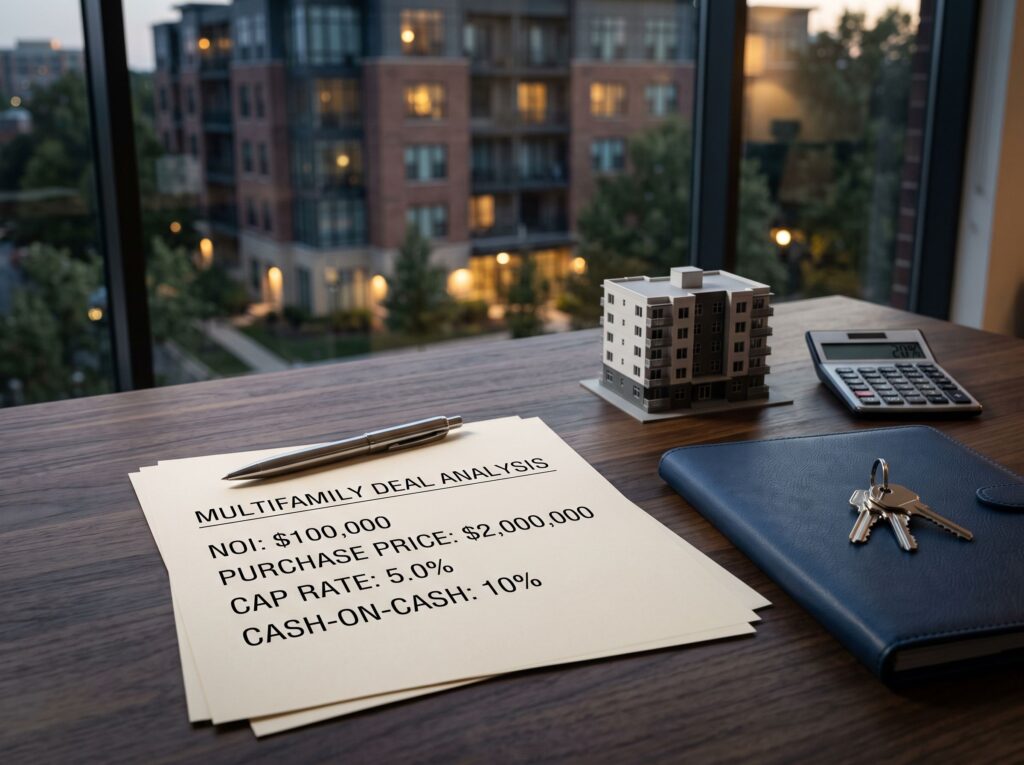
The cap rate is the property net operating income divided by its purchase price. If a building generates $100,000 in net operating income and you buy it for $2 million, the cap rate is 5%. Cap rates vary by market and property quality. Small multifamily cap rates have averaged around 6.0% in recent quarters, according to Arbor Small Multifamily Investment Trends Report. New-issue multifamily CMBS loans have shown cap rates around 5.45%. Higher cap rates mean higher yields but often come with more risk or older properties.
Cash-on-cash return measures the cash flow you receive each year relative to the cash you invested. If you put $300,000 down and the property generates $30,000 in cash flow after debt service, your cash-on-cash return is 10%. That is the number that determines whether the deal makes sense for your portfolio.
| Metric | What It Tells You | Benchmark |
|---|---|---|
| Net operating income | Rent minus operating expenses, taxes, insurance, maintenance, and management | Verify every expense, do not trust seller numbers |
| Cap rate | Yield on the purchase price before debt | Compare to similar buildings in the same market |
| Cash-on-cash return | Annual cash flow relative to the cash you invested | The number that decides if the deal fits your portfolio |
| Debt service coverage | Net operating income divided by annual mortgage payment | Lenders want at least 1.25x |
| Vacancy rate | Percentage of units currently empty | Compare to the local market average |
| Rent growth potential | Whether current rents sit below market | Underwrite 3% to 3.5% over a five-year hold |
| Deferred maintenance | Repairs needed soon, roof, HVAC, plumbing | Can run into tens of thousands of dollars |
| Exit strategy | How you will sell or refinance out of the deal | Define the expected hold period upfront |
CBRE outlook suggests buyers are underwriting rent growth at 3% to 3.5% over a typical five-year hold, with exit cap rates flat or up 25 basis points. If your deal requires 8% rent growth to work, you are taking on more risk than the market assumes. Be conservative with your projections.
Financing Options
Financing is where most first-time multifamily investors get stuck. The loan products are different from residential mortgages, and the qualification standards are stricter. Here is what is available right now.
For properties with two to four units, you can still use residential financing if you plan to live in one of the units. FHA loans allow owner-occupants to buy with as little as 3.5% down, and you can use rental income from the other units to qualify. VA loans offer no down payment for eligible service members. Conventional owner-occupied loans typically require 5% to 15% down. These are the easiest entry points for new investors.
Once you get to five units or more, you are in commercial loan territory. Down payments typically run 20% to 30%, and the lender focuses on the property income rather than your personal finances. Fannie Mae and Freddie Mac are the biggest players in this space. They offer competitive fixed rates, often in the 5.5% to 6.5% range, with loan terms of 5, 7, or 10 years. The FHFA set their multifamily loan purchase caps at $88 billion each, for a combined $176 billion.
| Loan Type | Typical Down Payment | Best For |
|---|---|---|
| FHA owner-occupied | 3.5% | First two to four unit purchase you live in |
| Conventional owner-occupied | 5% to 15% | Small multifamily with better credit and reserves |
| Agency loans, Fannie and Freddie | 20% to 30% | Stabilized five unit plus properties at competitive fixed rates |
| Bank loans | 20% to 30% | Local properties where you have a banking relationship |
| CMBS loans | 20% to 30% | Larger properties, no personal guarantee required |
| Life company loans | 25% to 35% | High-quality stabilized assets, usually $5 million and up |
| Bridge loans | 20% to 30% | Value-add deals that need renovation before refinancing |
| Seller financing | Negotiable | Smaller properties where bank qualification is difficult |
Current apartment mortgage rates range from 5.75% to 13.24% depending on the loan type, property quality, and borrower profile. Agency loans from Fannie and Freddie are at the lower end of that range. Bridge and hard money loans are at the higher end. Many owners who financed properties when rates were near 3% are now facing refinancing at rates near 6%, which has forced some to sell. That creates opportunities for buyers with capital.
Syndication vs. Direct Ownership
There are two main ways to invest in multifamily: you can buy a property yourself, or you can invest in someone else deal through a syndication. Each path has a different level of involvement, risk, and return potential.
Direct ownership means you buy the property, arrange the financing, manage the renovations, and handle the tenants. You keep all the cash flow and all the appreciation. You also handle all the problems. If a pipe bursts at 2 AM, you get the call. If a tenant stops paying, you deal with the eviction. Direct ownership gives you full control, but it also requires time, expertise, and a willingness to learn property management or hire someone who knows it.
A syndication is a private investment where a sponsor, called the general partner, raises money from a group of investors, called limited partners, to buy a specific property. The sponsor finds the deal, manages the property, and handles the day-to-day work. You put up capital and collect a share of the cash flow and profits. Syndications are almost always limited to accredited investors, which the SEC defines as someone with a net worth over $1 million (not counting their primary home), annual income over $200,000 individually or $300,000 jointly, or a qualifying professional credential like the Series 7, 65, or 82 license. Our guide to real estate syndications compares them against REITs and crowdfunding in more detail.
| Factor | Direct Ownership | Syndication |
|---|---|---|
| Capital required | 20% to 30% down plus closing costs and reserves | $25,000 to $100,000, with $50,000 most common |
| Qualification | Open to anyone who can qualify for the loan | Almost always accredited investors only |
| Time commitment | High, tenants, repairs, bookkeeping, leasing | Low, the sponsor runs everything |
| Upside | You keep 100% of cash flow and appreciation | Sponsor takes 20% to 30% of profits above a 7% to 9% preferred return |
| Target returns | Depends entirely on the deal you buy | 14% to 20% IRR on value-add, 10% to 13% on stabilized |
| Liquidity | Sell the property when you choose | Locked for two to seven years |
Direct ownership gives you control and full upside. Syndication gives you a passive investment and a share of the upside. Neither is better. They just serve different investors.
If you want to be hands-on and you have the time and capital to manage a property, direct ownership can build significant wealth. If you want a passive investment and you qualify as an accredited investor, a syndication lets you participate in deals that would be out of reach on your own. Many investors start with direct ownership of a small property, build experience, and then move into syndications as limited partners when they want to scale without adding management responsibilities.
If you are not accredited, you can still get real estate exposure through public REITs or crowdfunding platforms. Those options have their own trade-offs, but they give non-accredited investors a way to participate.
Market Selection
Where you buy matters as much as what you buy. A great property in a bad market can underperform a mediocre property in a strong market. The best markets combine job growth, population growth, affordable housing, and limited new supply.
Arbor Opportunity Matrix ranked Indianapolis first among the 50 largest US metro areas, supported by strong labor market conditions, tight occupancy levels, and a favorable affordability profile. Raleigh, Salt Lake City, and Nashville rounded out the top five, driven by population growth and performance fundamentals. Midwestern markets, which feature stability, affordability, and steady renter demand, captured seven of the top 20 spots.
Other markets worth watching:
- ▸ Chicago: Posted 3.2% annual rent growth in January and ranked in the top 10 on multiple opportunity lists.
- ▸ Miami and Fort Lauderdale: Strong population growth and limited supply have kept fundamentals tight. Fort Lauderdale ranked first among 50 major markets in one recent analysis.
- ▸ Dallas: Continues to lead as the top investment market for commercial real estate overall, though multifamily supply has been heavy.
- ▸ San Francisco and New York: Gateway markets with steep barriers to homeownership and strong long-term demand, though entry prices are high.
The biggest concern right now is oversupply in some Sun Belt markets. New apartment deliveries surged over the past two years, and markets like Austin, Phoenix, and Atlanta are still absorbing that supply. A recent JBRec survey found that 43% of multifamily investors listed oversupply as their top concern, up sharply from just 17% who cited interest rates. That oversupply has pushed vacancy rates above historical norms in some markets and limited rent growth.
When you evaluate a market, look at the supply pipeline. How many new units are under construction? How does that compare to historical absorption? Markets with limited new supply and steady job growth are the safest bets. Markets with a flood of new units are riskier, but they can also offer buying opportunities if sellers are forced to sell at a discount.
Do not chase the market with the highest rent growth. Chase the market with the best balance of supply and demand.
The Bottom Line
Multifamily real estate offers a path to steady cash flow, tax advantages, and long-term appreciation. The sector has plenty of capital available, with Fannie Mae and Freddie Mac lending capacity at $176 billion. Cap rates have stabilized around 6% for small multifamily properties, and rent growth is projected at 3% to 3.5% over a typical hold period.
The key is to buy right. Run the numbers on every deal, use conservative projections, and pick markets with a healthy balance of supply and demand. If you want to be hands-on, direct ownership gives you control and full upside. If you want a passive investment and you qualify as an accredited investor, a syndication lets you participate in larger deals without managing the property.
Start by deciding how much capital you can deploy and how much time you want to spend. Then look at markets, run the numbers on a few deals, and talk to lenders about financing. Before you commit, check your asset allocation so one property does not dominate your net worth. The first deal is always the hardest. After that, it gets easier.
Frequently Asked Questions
How do I start with multifamily?
Start small. Buy a duplex, triplex, or fourplex using an FHA or conventional owner-occupied loan. Live in one unit and rent the others. That gives you hands-on experience with tenants, maintenance, and bookkeeping without the complexity of a commercial loan. After a few years, you can use the equity and experience to buy a larger property or move into syndications as a limited partner.
What markets are best?
The best markets combine job growth, population growth, affordable housing, and limited new supply. Indianapolis, Raleigh, Salt Lake City, and Nashville rank highly on opportunity matrices. Midwestern markets offer stability and affordability. Sun Belt markets have stronger growth but more supply risk. The right market for you depends on where you live, how hands-on you want to be, and how much capital you have.
How much do I need?
For direct ownership, expect to put 20% to 30% down on a commercial loan, plus closing costs and reserves. On a $1 million property, that means $200,000 to $300,000 out of pocket. For a smaller owner-occupied property, FHA loans allow 3.5% down, so you could get started with $15,000 to $20,000 on a $400,000 fourplex. For a syndication, minimums typically range from $25,000 to $100,000, with $50,000 being the most common.